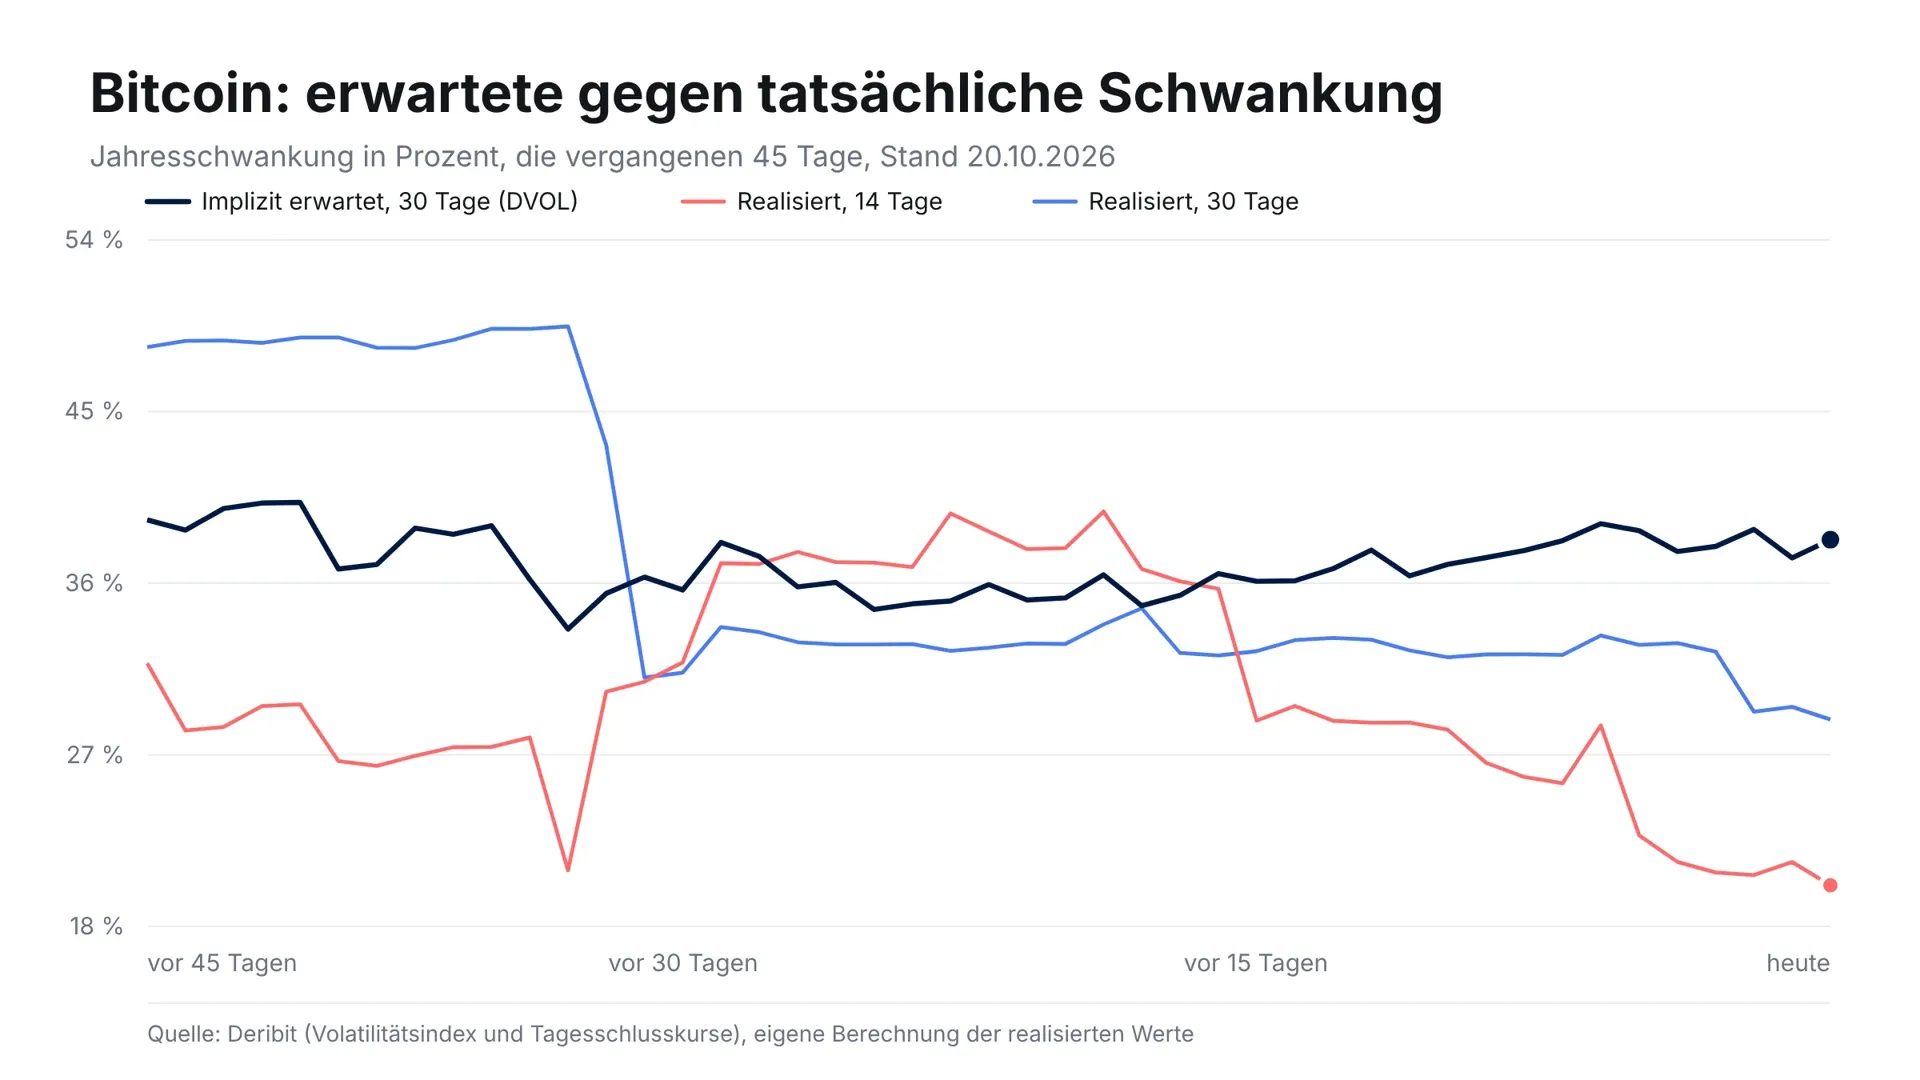
The options market is pricing Bitcoin volatility at 38.3 percent a year. Over the past two weeks the price has delivered 20.2 percent. That gap of just over 18 points is the real news this Tuesday, and it says more about the coming weeks than the price level itself. Bitcoin traded at $81,481 on Tuesday afternoon, about 1.3 percent below Monday’s level.
What the DVOL volatility index is showing right now
DVOL is Deribit’s Bitcoin volatility index. It condenses the prices of all traded options with roughly 30 days left to run into a single number: the expected range of movement, annualised. At 38.3, the market expects Bitcoin to vary by a good 38 percent around its path over the next twelve months. At 12:00 Coordinated Universal Time on Tuesday the index stood at 38.28, against 38.17 on Monday and 38.23 a week earlier.
The number says nothing about direction. A high DVOL does not mean the price will rise or fall, only that a forceful move either way is expected and paid for. That is precisely why it is worth comparing with what has actually happened.
38.3 against 20.2 percent: the true size of the gap
Realised volatility looks backwards. It takes the daily price changes over a period and measures how widely they are spread. On that basis Bitcoin comes to 20.2 percent over the past 14 days, 28.9 percent over 30 days and 25.4 percent over seven days. The basis is the daily closing prices of the Deribit perpetual contract, and we converted them ourselves.
Translated into daily moves, the gap becomes tangible. A DVOL of 38.3 percent corresponds to roughly 2.0 percent of movement on an average trading day. The realised 20.2 percent corresponds to 1.06 percent. The derivatives market is therefore paying for almost twice the movement Bitcoin has recently delivered.
How a volatility premium arises
A volatility premium is the mark-up option buyers pay above the swings that actually materialise. The premium exists because an option is insurance: whoever buys one is hedging against a large move and pays a price that embeds the expected volatility. Whoever sells one collects that price and carries the risk that the move arrives after all.
If the market stays calm, the seller earns on every day that nothing happens, because the option’s time value melts away. If the price breaks out, the seller’s loss can be a multiple of the premium collected. That asymmetry sits behind the current set-up, and it explains why experienced traders are turning cautious now: a premium 18 points above delivered volatility is either a gift or a warning.
What 38.3 percent means for the next 30 days
A range can be derived from DVOL. Annualised 38.3 percent works out at roughly 11.0 percent over 30 days. Applied to a price of $81,481, that gives a range of about $72,500 to $90,400, within which Bitcoin should trade until mid-November with a probability of around two-thirds on that expectation.
The calculation is a derivation from market prices, not a forecast. The formula behind it assumes an even distribution of moves, which never holds in a crisis. It still serves for orientation: anyone whose portfolio cannot withstand a drop to $72,500 should not hold the position, because that figure sits inside the market’s normal expected range rather than at its edge.
The 50-day average at $81,580 as a hinge
The price is glued to its 50-day average. The daily closes of the past 50 trading days give a mean of $81,580, and the last close was $81,554. The distance is 0.03 percent. A line a price sits this close to acts as a hinge and decides nothing until the price leaves it, upwards or downwards, on volume.
Above sits last week’s daily high at $83,200, below it the weekly low at $79,710. Those two values frame the area Bitcoin has moved in since October 14. A daily close outside it would be the first signal that the expected move is actually beginning.
What the derivatives market charges in running costs
Anyone holding Bitcoin through a perpetual contract pays the funding rate. At Deribit it stood at 0.0035 percent per eight hours on Tuesday. Annualised, that is 3.87 percent a buyer hands to the other side purely for keeping the position open. Open interest in the perpetual contract was $856 million.
Where the options for October 30 sit
The monthly expiry on October 30 carries 148,585 Bitcoin in open interest, around $12.1 billion at the current price. The ratio of puts to calls is 0.50, so twice as many calls are outstanding. The calculated point of maximum pain, where the largest share of all contracts expires worthless, lies at $78,000.
The distribution explains the calm. The large clusters of calls sit at $95,000 with 25,567 contracts, at $90,000 with 15,302 and at $100,000 with 14,312. All three are 10 to 23 percent above today’s price and therefore outside the range DVOL is pricing in for the next 30 days. Those contracts tie up capital without moving the price. The puts cluster at $70,000 with 4,389 contracts and at $75,000 with 3,037.
Leverage, holding period and purchase route for investors in Germany
That figure of 11.0 percent allows a sober calculation for leveraged positions. At ten times leverage the liquidation threshold sits roughly ten percent from the entry, before maintenance margin and fees. That distance is smaller than the monthly move the options market is currently pricing as normal. Leverage of ten is, under these conditions, a bet that the premium is set too high, not a safety margin.
On the purchase route, the European regulation on markets in crypto assets, MiCA for short, has applied in full since this year, which means providers in Germany need authorisation. Buy Bitcoin through a licensed exchange and then move it to your own wallet, and you hold the coin yourself and pay no running funding rate. That is the difference between a holding and a position.
Our view of the current set-up
In the view of this newsroom, the data argues for a resolution upwards or downwards within the next two to three weeks rather than a continuation of the calm. The evidence: realised 14-day volatility has fallen from 39.8 percent on October 2 to 20.2 percent, the lowest reading in the 45-day measurement window. At the same time the options market is holding on to 38.3 percent and has not lowered that expectation for a week. Traders who risk money daily are therefore reckoning with an end to the quiet.
Against that, this very constellation has been in place since the start of October and has so far triggered nothing. A premium can persist for weeks without unwinding, and in any case it says nothing about direction. Anyone deriving a buying decision from this set-up is confusing volatility with direction. For a portfolio, that means the size of the position deserves a review, not its direction.
Volatility premium: $72,500 and $90,400 frame the picture
Three steps follow from the set-up:
- Work out whether your portfolio can withstand a drop to $72,500. That value lies inside the options market’s normal expected range, not at its edge.
- For leveraged positions, compare the distance to liquidation with the 11.0 percent the market is pricing as a monthly move. Providers’ terms are set out in our perp DEX comparison, and spot exchange fees in our exchange comparison.
- Note the purchase date for every holding so the one-year period stays provable. The tools for that are in our crypto tax software comparison.
(As of October 20, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)